It was one of the most famous and most devastating campaign slogans in modern political history: Are you better off than you were four years ago? Australians know the answer to that one, in 2026: Shit, no. In fact, we’re worse off than we were back when first-time voters at the next election were nothing more than a root in the back seat of a Holden Commodore.
Oddly enough, a Labor government was in power back then, too. Remember when they scoffed at John Howard for saying that interest rates would be worse under a Labor government?
Australians are worse off today than they were 18 years ago at the height of the global financial crisis, the last time the official cash rate was higher than it is now after the Reserve Bank’s latest hike, with hundreds of homeowners forced to list their homes for sale over the past four weeks.
On Tuesday, the Reserve Bank lifted the cash rate by 0.25 percentage points to 4.85 per cent, the fifth hike this year and the highest level since November 2008. The decision was not unanimous: six board members voted for the hike, three for holding. Even the people paid to get this right can’t agree on how wrong it is.
The Australian has done the sums on how that compares with 2008, and the result is grim. The average owner-occupier mortgage has swollen from $254,000 to $731,000, an increase of 188 per cent. Monthly repayments on a new loan have gone from $1,835 to $4,631. Meanwhile, the average full-time ordinary wage has risen from $1,164.90 to $2,083.70 a week, a paltry 79 per cent. Disposable income managed 69 per cent. You can’t pay a mortgage that has nearly tripled with a pay packet that hasn’t doubled. Arithmetic is the one thing Labor can’t spin.
Nor is it only the mortgage. Average weekly spending on goods and services, food, electricity and travel included, has leapt from $1,175 to $2,856, up 143 per cent. A non-bulk-billed visit to the GP has gone from $19.50 to $49, up 151 per cent. Petrol, curiously, has risen only 80 per cent, from $1.33 to $2.40 a litre, which is to say, in line with wages. Fuel is the one item in the household budget that hasn’t been robbed in broad daylight and it still costs $2.40.
The human cost is already showing. Hundreds of homeowners have been forced to list their homes in the past four weeks, and Experian reports a 7.3 per cent rise in home loan accounts under strain in the first half of 2026, concentrated in regional areas and among millennial and Gen X borrowers. So much for ‘generational equity’. These are the people who did everything they were told: work hard, buy a house and take on a mortgage. Now they’re being told the reward is a distressed sale.
REA Group’s senior economist Angus Moore offered the sort of consolation economists specialise in:
“While the economy has slowed, and the labour market has eased a bit in recent months, the RBA is yet to be convinced that inflation will return sustainably to target without further tightening.”
Translated from the dialect of the dismal science: it’s going to get worse before it gets worse. The RBA’s own forecasts see inflation staying high through much of 2027, not falling below three per cent until late that year, “around three quarters later than previously forecast”. Unemployment, now 4.7 per cent, is projected to climb to 5.1 per cent. And since a rate change takes 12 to 18 months to flow through the economy, we won’t know what this hike has done until 2028. Just in time to vote the bastards out.
Governor Michele Bullock, asked whether the bank risked pushing the country into recession, didn’t think of the obvious answer: it’s Albanese government doing the shoving. Instead, she insisted the RBA was ‘not looking to tip the economy into recession if we can avoid it’. Well, gee, that’s big of her. She did concede that Australians would ‘feel poorer’, because ‘we’re all poorer’.
Not a word about who made us so.
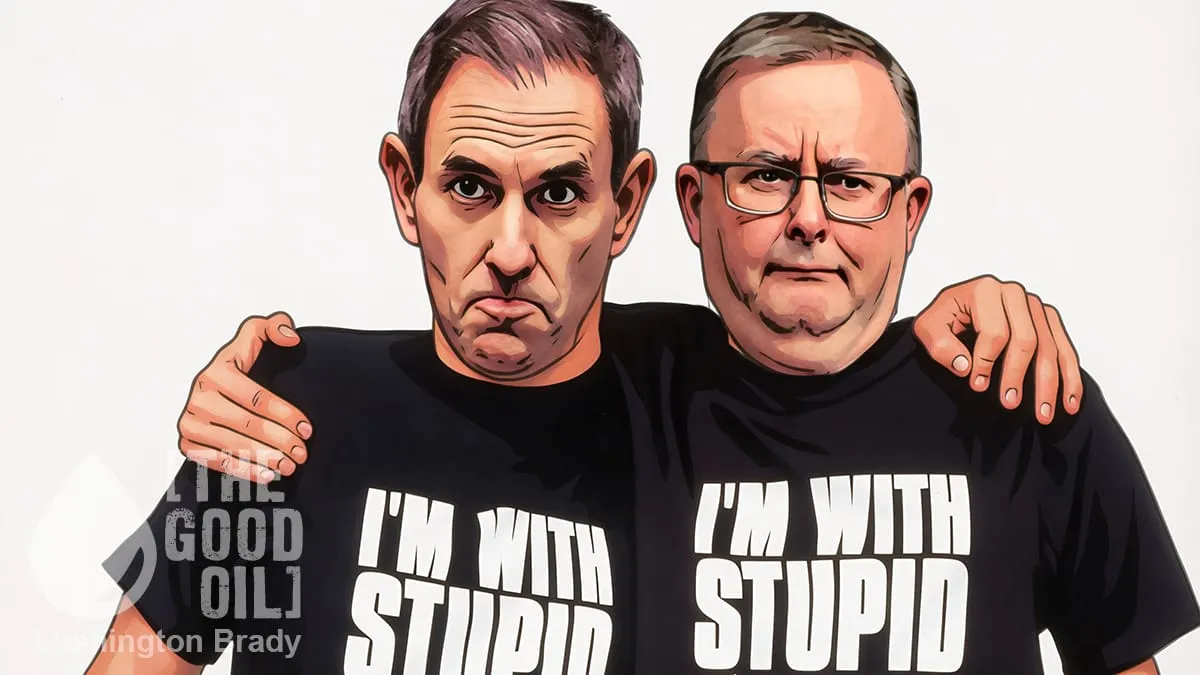
And who might answer for it? Treasurer Jim Chalmers, naturally, who was left to front the music while Anthony Albanese schmoozed Commonwealth leaders in the Caribbean. Not even the prime minister’s holiday could distract from the treasurer’s polling. Newspoll has Chalmers at a net approval of minus 16, the worst of any minister, though still better than Albanese’s minus 23.
Pressed on whether he’d thought about stepping aside and “giving someone else a go”, the treasurer said: “No.”
Spoken like a man who has never once had to ring his bank manager to beg for an extension. Four years ago, the line was ‘are you better off?’ Today, the question is whether anyone in Canberra gives a rat’s arse that you aren’t.